
Article Operations 2 min read
Storm-Battered Associations Lean on Business Interruption Insurance
Claims on business interruption policies are helping associations weather the aftermath of Hurricane Sandy.
Heads up: this content is over 5 years old, so some information may be out of date.
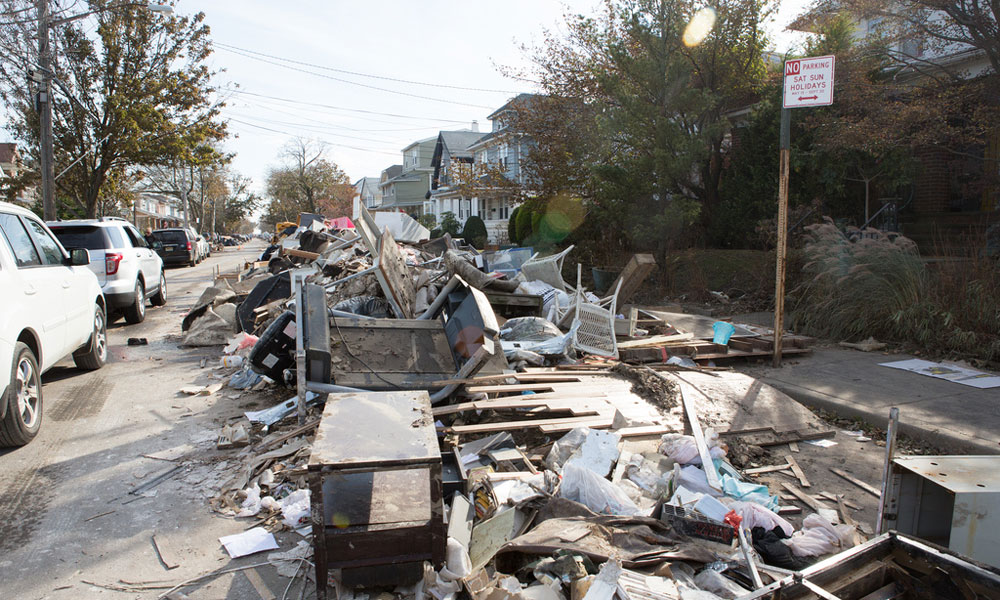
Recovery efforts are far from over in New York and New Jersey following the devastation from Hurricane Sandy. But businesses and associations are trying to get back up and running while office buildings are still flooded or without power. That’s where business interruption insurance offers a helping hand.
“It will provide coverage for certain occurrences where your business cannot operate,” said Michelle Evans, assistant vice president of Aon Association Services, a division of Affinity Insurance Services, Inc. “We have quite a few associations in the New York and New Jersey area, and we have received calls where they cannot operate and they are in the process of using that coverage as we speak.”
The coverage has helped groups whose buildings were destroyed get set up in another location and continue to operate. Some associations have also made claims to cover rent, electricity bills, and other operating expenses that can become a burden while an office building is inaccessible.
Business interruption insurance is typically bundled in an office package policy—synonymous with a business owners’ policy. “There’s not an actual dollar amount assigned” in an office package policy, said Evans. “Usually it is actual loss sustained not to exceed 12 consecutive months, so it will keep you up and running for up to a year.”
Associations can also have a package policy designed specifically for their needs, but in those cases there’s usually a dollar amount assigned.
“Not every association will have an office package policy, and that’s the key here,” Evans said. “You might hear very small associations say, ‘I don’t need an office package, there’s no reason for me to have an office package.’ [Events like Hurricane Sandy are] the reason you need an office package policy.”
But it doesn’t take large-scale disaster like the Frankenstorm to trigger the coverage. A power outage, fire, or water damage could halt business as usual for an association and provide a basis for a claim.
“Business interruption coverage is for when there’s an interruption in your daily activity,” said Evans. “That’s what associations really need to take into consideration. It’s one of those coverages that individuals don’t think about until you need it.”
(U.S. Department of Labor/Flickr)
Comments
Comments are for ASAE members. Learn more about comments on this site.
Log in to your member account or join ASAE!